
Buying or selling a business is one of those decisions where a small mistake in valuation can become a very expensive problem. A seller who relies on an optimistic asking price may struggle to attract serious buyers. A buyer who focuses only on reported profit may pay for earnings that disappear after the owner leaves a major customer changes suppliers or previously hidden liabilities surface.
The challenge is that a business does not have one obvious “price.” Its value depends on sustainable earnings, future cash generation, assets, liabilities, market conditions, customer quality, management strength, legal obligations, and the structure of the transaction. Professional valuation standards therefore recognize different approaches including market, income and cost approaches depending on what is being valued and why.
This is especially important when buying or selling a company in Dubai or elsewhere in the UAE. Corporate Tax, Free Zone status, related-party transactions, licenses, working capital, and transaction structure can all affect what a buyer should actually pay. WBS Advisory likewise identifies valuation, due diligence, legal and operational assessment, risk review, and negotiation as important parts of the UAE business acquisition process.
Understand What “Business Value” Actually Means
The first mistake in many transactions is treating valuation, asking price, and the amount a seller receives as the same number. They are not.
A valuation estimates the economic worth of the business based on defined assumptions. The International Valuation Standards Council describes market value around the concept of a transaction between knowledgeable, willing parties acting at arm’s length without compulsion. It separately recognizes investment value the value of an asset to a particular owner or prospective owner which may be different because a specific buyer can have unique objectives or synergies.
That distinction matters in real transactions. A logistics company worth AED 10 million as a standalone operation might be worth more to a larger logistics group that can immediately use its warehouses, contracts, fleet, or customer relationships. The additional strategic value belongs to the negotiation; it should not automatically be built into the seller’s base valuation.
You also need to distinguish enterprise value from equity value. Enterprise value broadly reflects the value of the operating business, while equity value reflects what belongs to shareholders after considering debt and cash. CFA Institute defines enterprise value by reference to equity, debt and other capital claims, less cash and investments.
For sellers, this means an “AED 15 million valuation” is incomplete unless the parties know whether that figure refers to enterprise value or equity value. For buyers, understanding the difference prevents a headline valuation from hiding debt and other obligations that effectively increase the acquisition cost.
Build the Valuation From Evidence, Not the Asking Price
A valuation becomes useful only when it starts with financial information that reflects how the business genuinely performs.
Ideally, review several years of income statements and balance sheets together with current management accounts, bank activity, tax records, customer data, debt schedules, leases, payroll, capital expenditure and major contracts. The goal is not simply to confirm that revenue existed. It is to determine how much sustainable economic benefit the company produces.
Normalize Earnings Before Applying a Multiple
Reported profit is often a poor starting point for valuing an owner-managed business.
Imagine a Dubai services company reporting EBITDA of AED 1.5 million. During the year, however, it paid AED 300,000 for a one-off office relocation and AED 200,000 of personal expenses through the company. Removing genuinely non-recurring or non-business expenses could increase normalized EBITDA to AED 2 million.
The opposite can also happen. Perhaps the founder manages sales and operations but receives almost no salary. A new owner would need to employ a general manager at AED 400,000 per year. That replacement cost should normally reduce sustainable earnings rather than be ignored.
Quality-of-earnings work commonly examines proposed EBITDA adjustments, unusual or non-recurring items, revenue recognition and normalized working capital precisely because those issues can materially affect transaction economics.
Typical normalization questions include:
- Are owner salaries, personal expenses, related-party rent and management charges commercially reasonable?
- Did this year’s earnings include exceptional income or unusual costs that are unlikely to recur?
- Are doubtful receivables, obsolete inventory or under-recorded expenses overstating profitability?
- Would the company need additional employees, rent, systems or capital expenditure after the existing owner exits?
- Are earnings dependent on one unusually large customer, supplier or project?
UAE businesses should pay particular attention to related-party adjustments. The Federal Tax Authority states that UAE transfer-pricing requirements apply to transactions with Related Parties and Connected Persons, including domestic transactions and dealings involving mainland and Free Zone entities. A valuation should therefore not casually assume that below-market rent, management charges or shareholder arrangements will continue indefinitely.
Cross-Check the Business With the Right Valuation Methods
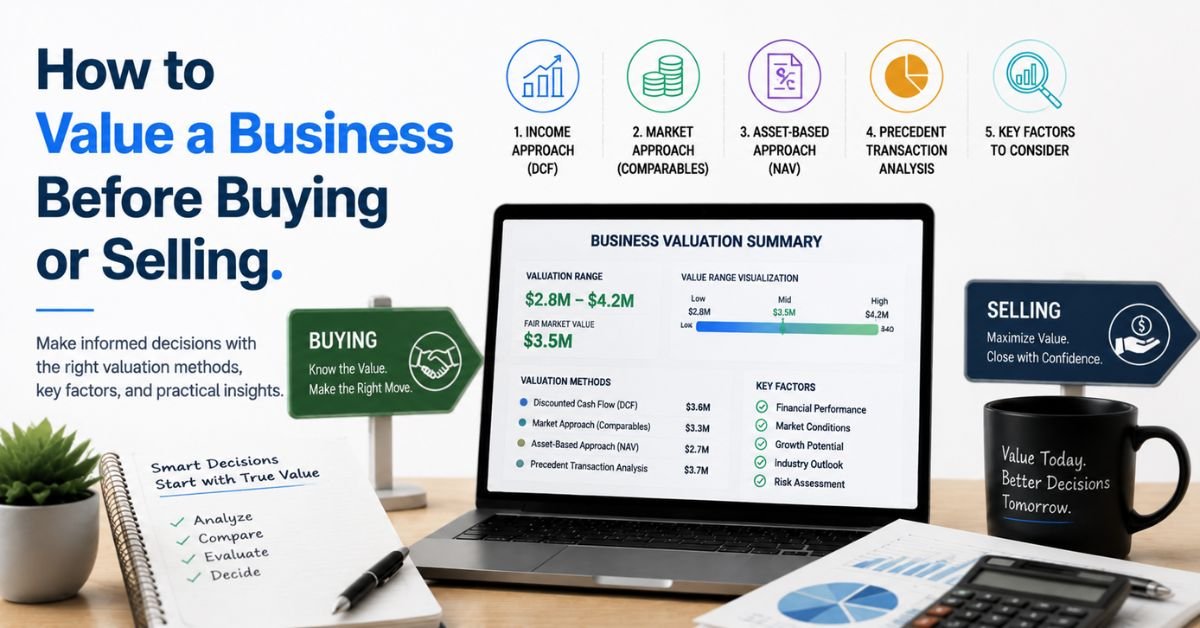
There is rarely a good reason to rely blindly on a single formula. The IVSC’s framework recognizes market, income and cost approaches, while its business-specific standards cover the valuation of businesses and business interests.
The market approach compares the company with similar businesses or transactions for which pricing information is available. In an SME transaction, a buyer might apply an EV/EBITDA multiple to normalized EBITDA. The difficult part is not multiplication; it is choosing truly comparable businesses. A fast-growing company with recurring contracts, low customer concentration and experienced management should not automatically receive the same multiple as a company with unstable earnings simply because both operate in the same industry.
The income approach, most commonly represented by discounted cash flow in business transactions, converts expected future cash flows into a current value. IVSC defines the income approach in essentially those terms. DCF can be particularly useful when future performance is expected to differ significantly from historical earnings. However, aggressive revenue forecasts, unrealistic margins or understated investment requirements can produce an impressive-looking but misleading valuation.
The asset or cost approach becomes more relevant when tangible assets are a major source of value. IVSC describes the cost approach around what it would cost to obtain an asset of equivalent utility. A property-holding, equipment-intensive or industrial company may therefore require careful analysis of land, machinery, inventory and liabilities. For a consultancy, software company or other business whose value comes primarily from customers, employees, intellectual property and earnings, net book assets alone may substantially understate economic value.
The strongest valuation usually explains why different methods produce different results rather than simply averaging them.
Turn the Valuation Into the Real Transaction Price
Suppose normalized EBITDA is AED 2 million and appropriate comparable evidence supports a 4.5× multiple. That suggests an enterprise value of AED 9 million.
The negotiation is still not finished.
Assume the business has AED 1.2 million of debt and AED 300,000 of surplus cash. A simplified enterprise-to-equity bridge gives:
AED 9.0 million enterprise value – AED 1.2 million debt + AED 0.3 million cash = AED 8.1 million equity value.
Real transactions may also include debt-like liabilities, shareholder loans, unpaid bonuses, tax exposures, lease-related obligations or other agreed adjustments. The definition of “debt,” “cash” and similar items therefore needs to be clearly documented rather than assumed.
Working capital can also change the final cheque. Financial due diligence normally analyzes historical working-capital trends to establish a normalized level or “peg.” A seller should not be able to increase proceeds simply by collecting receivables aggressively and delaying normal supplier payments immediately before completion, leaving the buyer to inject cash the following week.
This is why buyers should test more than the spreadsheet valuation. Customer concentration, recurring versus project revenue, contract duration, supplier dependence, management depth, intellectual property ownership, pending disputes, employee retention and necessary capital expenditure all influence how dependable future earnings really are.
A valuation gives you a negotiating range. Due diligence determines whether the company deserves to remain within that range.
Account for UAE-Specific Factors That Can Change Value
UAE valuations now need to incorporate tax more explicitly. The UAE Corporate Tax regime generally applies a 0% rate to taxable income up to AED 375,000 and a 9% rate above that threshold for businesses subject to the standard regime. Because an income-based valuation depends on future after-tax economics, forecasts should reflect the company’s actual tax position rather than simply extrapolating historical pre-Corporate-Tax results.
Free Zone status also requires careful analysis. A Free Zone license does not automatically mean that every dirham of profit should be modeled at 0% Corporate Tax. The FTA states that a Qualifying Free Zone Person may benefit from a 0% rate on Qualifying Income, subject to relevant conditions, while taxable income outside the qualifying treatment can be subject to 9%. Buyers should therefore verify whether assumptions about Free Zone tax treatment are sustainable after ownership changes and under the buyer’s intended operating model.
Deal structure matters as well. A share acquisition and an acquisition of selected business assets can produce different legal, commercial and tax consequences. The FTA maintains specific guidance on the transfer of a business as a going concern for VAT purposes, making transaction-structure analysis an issue to address before not after the price is agreed.
Finally, do not assign full value to a trade license, lease, regulatory approval, customer agreement or supplier relationship until its continuity has been verified. The commercial value of a company can change quickly when an important contract cannot be transferred, a key approval requires additional steps, or the business depends heavily on relationships held personally by the existing owner.
For this reason, valuation should sit alongside financial, tax, legal and commercial due diligence. WBS Advisory’s UAE buy-and-sell service similarly combines business valuation with due diligence, risk assessment, transaction support and negotiations for buyers and sellers.
Conclusion
A good business valuation does more than attach a multiple to last year’s profit. It answers a more useful question: what sustainable economic value will actually transfer from the seller to the buyer?
Start by normalizing earnings. Then assess the business using valuation methods suited to its economics, reconcile enterprise value with debt, cash and working capital, and test the assumptions through due diligence. In the UAE the analysis should also reflect Corporate Tax, Free Zone conditions, related-party arrangements, VAT considerations, licensing requirements and the exact structure of the transaction.
For sellers, doing this work before going to market can reveal weaknesses that should be corrected and value drivers that deserve to be highlighted. For buyers, it creates a disciplined ceiling on what to pay and reduces the risk of discovering after completion that the acquired earnings were less sustainable than they appeared.
Ultimately, the objective is not to produce the highest possible valuation or the lowest possible offer. It is to establish a defensible value that can survive financial scrutiny, due diligence and negotiation and then structure a transaction in which both parties understand exactly what is being bought and sold.
FAQs
How do you calculate the value of a small business in the UAE?
Start with normalized sustainable earnings and assess them using suitable market multiples, an income-based valuation such as DCF, or an asset-based approach. The appropriate method depends on the company’s industry, assets, growth, risk and quality of financial information.
What is the most common mistake sellers make when valuing a business?
Using an asking price or optimistic profit figure without normalizing owner expenses, one-off items, replacement management costs, working capital and other adjustments that a serious buyer will examine during due diligence.
Is EBITDA enough to value a company?
No. EBITDA can be useful when applying market multiples, but the multiple itself depends on factors such as growth, risk, customer quality and business sustainability. Cash requirements, debt, taxes and capital expenditure also matter.
Does a Free Zone company automatically get valued using 0% Corporate Tax?
No. The FTA’s 0% Free Zone Corporate Tax treatment applies to Qualifying Income of a Qualifying Free Zone Person subject to the required conditions; other taxable income may be subject to 9%.
Should I get a professional valuation before buying or selling a business?
For a material transaction, an independent, well-supported valuation can help establish a defensible negotiating range and identify assumptions requiring further due diligence. WBS Advisory specifically includes professional valuation, due diligence and transaction support within its UAE company buying and selling services.