
A business can have strong demand, an attractive product, and ambitious growth targets and still run into financial trouble. The problem is often not the business idea itself; it is the absence of a financial plan that connects market demand, pricing, operating costs, cash requirements, funding, and regulatory obligations.
That distinction matters in the UAE where businesses must plan not only for growth but also for VAT, Corporate Tax, financing requirements, and a changing financial-compliance environment. Corporate Tax is now an established part of doing business in the country, while the UAE’s Electronic Invoicing System has entered its implementation phase. These obligations can affect margins, cash timing, accounting systems, and administrative costs.
A strong business financial plan therefore does much more than predict whether a company will make a profit. It explains how the business will generate revenue, what it will cost to deliver that revenue, when cash will actually be received, how much capital will be required, and what happens when reality differs from the forecast.
Ground the Financial Plan in Market Reality
The first component of a credible financial plan is not a spreadsheet. It is a defensible set of assumptions.
Sales projections become unreliable when they begin with an arbitrary statement such as, “Revenue will grow by 20% next year.” A stronger forecast starts further upstream: Who will buy? How many potential customers can realistically be reached? What are they willing to pay? How frequently will they purchase? What alternatives are available to them? How much market share can the business reasonably capture?
This is why market research and financial planning should be connected. WBS Advisory’s market research framework includes customer profiling, competitive analysis, market requirements, trends and forecasting, and strategy development. Those inputs can directly strengthen the assumptions behind pricing, expected customer volumes, geographic expansion, product launches, and revenue forecasts.
Consider a Dubai-based B2B service provider planning to enter Abu Dhabi. A weak financial model might simply add AED 2 million of new revenue. A more useful model would identify the number of target companies, expected lead volume, conversion rate, average contract value, sales cycle, customer retention and additional sales staff required. Revenue then becomes the result of commercial assumptions rather than the assumption itself.
Market information should also challenge the plan. If competitors are discounting heavily, customers require 60-day payment terms, or the addressable customer base is smaller than expected, those findings belong in the financial model rather than being left in a separate market report. WBS Advisory specifically positions market research around customer understanding, risk reduction, competitor evaluation, forecasting, and strategic planning—all of which can affect financial assumptions.
Build Linked Revenue, Profit, and Balance-Sheet Forecasts
Once the commercial assumptions are established, they need to flow through a connected financial model. A serious plan should not consist of a sales target followed by an estimated year-end profit.
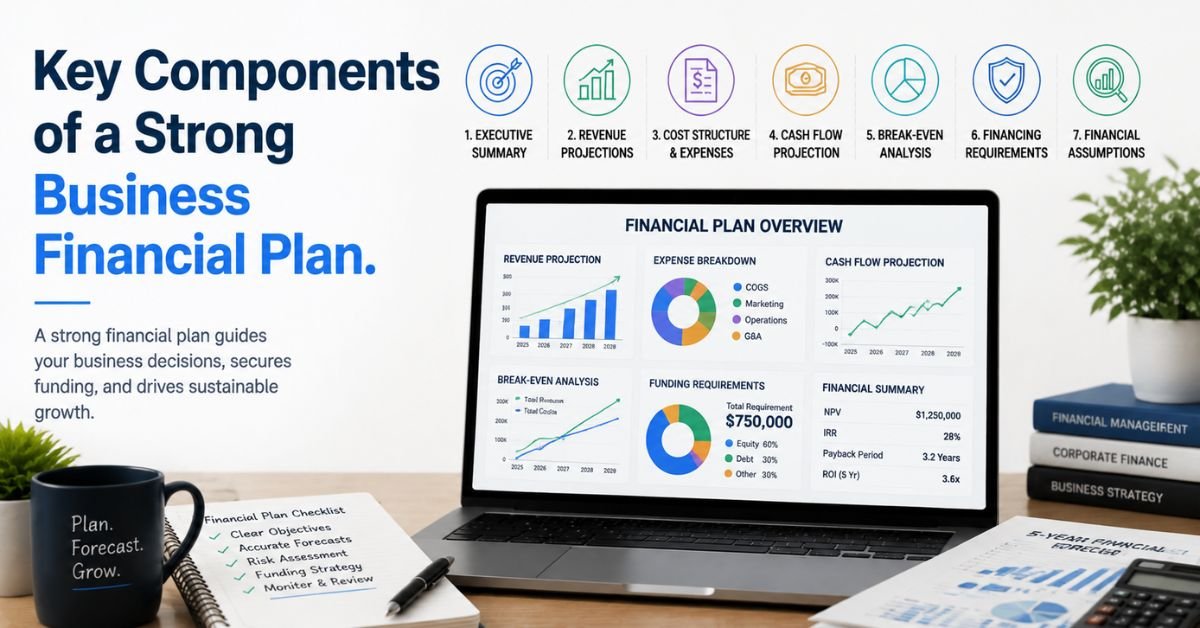
Core projections generally include:
- Profit and loss forecast: revenue, direct costs, gross profit, operating expenses, finance costs, and expected profit.
- Cash-flow forecast: when money is actually expected to enter and leave the bank account.
- Forecast balance sheet: expected cash, receivables, inventory, fixed assets, liabilities, debt, and shareholder equity.
- Capital expenditure plan: major investments in equipment, fit-outs, vehicles, systems, or other long-term assets.
- Break-even analysis: the level of sales required before the business covers its costs.
These statements should work together. Business-planning guidance from the U.S. Small Business Administration similarly treats forecast income statements, balance sheets, cash-flow statements, and capital expenditure budgets as interconnected parts of financial projections rather than isolated documents.
Revenue and Margin Assumptions Should Explain the Economics
The revenue forecast should be built from the commercial drivers appropriate to the business.
For a restaurant, those drivers could be available seats × table turns × occupancy × average customer spend. For an e-commerce company, they might be website traffic × conversion rate × average order value × repeat purchases. For a consulting firm, they could be billable consultants × utilization rate × billable days × average daily rate.
The same discipline should continue below revenue. Separate costs that move with sales from costs that remain relatively fixed. This makes it easier to understand contribution margin and break-even performance. The standard break-even relationship is fixed costs divided by the difference between selling price and variable cost per unit.
For example, increasing sales by AED 1 million sounds attractive. But if winning those sales requires AED 650,000 of additional product costs, AED 150,000 of commissions, another employee, and higher logistics expenses, management needs to evaluate the incremental profit and cash requirement, not the top-line figure alone.
That is the real purpose of financial planning: exposing the economics behind growth.
Protect Liquidity With Cash-Flow and Working-Capital Planning
Profit and cash are not interchangeable.
A company can record a profitable sale today but wait 30, 60 or 90 days to collect the invoice. Meanwhile, salaries, suppliers, rent, VAT payments, and other obligations may fall due much earlier. A business can therefore appear profitable on its income statement while experiencing serious liquidity pressure.
A cash-flow forecast should reflect when cash moves, not simply when revenue and expenses are recognized. Good cash planning therefore models customer collection periods, supplier payment terms, inventory purchases, payroll dates, tax payments, loan repayments, deposits, capital expenditure, and seasonal variations. British Business Bank guidance similarly emphasizes forecasting actual cash receipts and outgoings and maintaining a running cash position over the relevant cash-flow cycle.
Working capital deserves particular attention for UAE companies selling to corporate customers, operating inventory-heavy businesses, importing products, or expanding quickly. Faster growth can sometimes increase financing pressure because additional orders may require inventory, employees, or supplier payments well before the customer settles the invoice. Emirates Development Bank’s SME initiatives include working-capital, supply-chain, and invoice-related financing solutions, reflecting the practical importance of this issue for UAE businesses.
A useful plan should therefore identify a minimum cash balance—the point below which management does not want available liquidity to fall. The forecast can then show exactly when additional funding may be needed, rather than waiting until the bank balance becomes critical.
Match Funding and UAE Compliance Requirements to Growth
The financial plan should state exactly how much funding the business requires, when it requires it, what the money will finance, and how the capital will be repaid or generate returns.
For example, borrowing AED 1 million because “the company wants to expand” is vague. A better plan might allocate AED 350,000 to equipment, AED 250,000 to inventory, AED 200,000 to recruitment and training, and AED 200,000 to working-capital reserves. The model should then show how the investment affects revenue, cash flow, financing costs, and repayment capacity.
Cash-flow strength matters especially when debt is involved because repayments must be made from actual available cash not accounting profit. Lender-oriented guidance consequently gives considerable importance to cash-flow forecasting when evaluating whether a business can support financing.
For UAE businesses, compliance costs and taxes should also appear explicitly in the plan rather than being treated as year-end accounting adjustments:
- UAE Corporate Tax is generally 0% on taxable income up to AED 375,000 and 9% above AED 375,000, subject to the applicable rules and exceptions.
- Mandatory VAT registration generally applies to UAE-resident businesses when taxable supplies and imports exceed AED 375,000, while the voluntary-registration threshold is AED 187,500.
- Eligible resident businesses may currently elect for Small Business Relief where revenue does not exceed AED 3 million under the relevant conditions, but the present relief applies only to eligible tax periods ending on or before December 31, 2026. It should therefore not be treated as a permanent assumption in long-term forecasts.
- UAE e-invoicing is being phased in. The pilot began July 1, 2026 businesses with annual revenue of at least AED 50 million are scheduled for mandatory implementation from January 1, 2027 while businesses below that threshold are scheduled from July 1, 2027, subject to the official scope and requirements.
These items can affect tax provisions, technology budgets, accounting processes, professional fees, and working capital. The Federal Tax Authority also requires relevant Corporate Tax records to be retained for at least seven years, reinforcing the need for financial planning and record-keeping systems to develop together.
Use the Financial Plan as a Living Decision System
A financial plan loses much of its value when it is prepared for a loan application, investor presentation, or business launch and then left untouched.
The better approach is a rolling forecast. Each month, compare actual performance with the plan and investigate meaningful differences.
Suppose sales are 8% below forecast. The useful question is not simply, “Why did we miss the budget?” Management should trace the difference back to its drivers: Was customer traffic lower? Was conversion weaker? Did deals take longer to close? Did prices fall? Was one sales channel underperforming?
The same approach works with costs and cash. Higher gross profit but lower cash could point to slower customer collections. Higher revenue but lower margins might indicate discounting or increased supplier costs. Rapid sales growth accompanied by declining cash may reveal rising receivables or inventory requirements. Regular reforecasting incorporates these new facts into the next decision cycle rather than continuing to manage against assumptions that are no longer valid.
A useful management dashboard can focus on a small number of financial drivers: revenue versus budget, gross margin, operating profit, cash balance, receivable days, inventory levels where relevant, monthly cash burn, and available funding. The exact measures should reflect the economics of the business rather than copying a generic template. Cash-flow guidance specifically highlights indicators such as cash on hand, debtor days, inventory days, supplier days, and sales as useful forecasting measures.
This is also where continuous market intelligence becomes valuable. When customer preferences, competitors, pricing, or market opportunities change, those changes should feed back into revenue assumptions and investment decisions rather than remain disconnected from the financial model.
Frequently Asked Questions
What are the main components of a business financial plan?
A strong plan normally combines revenue projections, operating expenses, profit and loss forecasts, cash-flow forecasts, a projected balance sheet, capital expenditure, working-capital requirements, break-even analysis, funding needs, and relevant tax assumptions.
How far ahead should a business financial plan forecast?
The appropriate period depends on the business, but detailed monthly forecasting is particularly useful in the near term, with longer-range annual projections supporting strategic decisions. Formal business-plan guidance commonly uses multi-year projections while recommending greater detail during the first year.
Why is cash-flow forecasting important if the business is profitable?
Because revenue may be recognized before customers actually pay. A profitable company can still face difficulty paying suppliers, employees, taxes, or lenders when cash collections arrive later than its obligations.
How does market research improve a financial plan?
It provides evidence for assumptions such as customer demand, target segments, competitor positioning, pricing, market requirements and future opportunities. Those inputs make revenue and expansion forecasts more defensible.
How often should a business update its financial plan?
Actual results should be monitored regularly, with forecasts revised when significant differences, new contracts, lost customers, cost changes, financing decisions, or other material developments make the original assumptions outdated.