
Putting a value on business equity sounds straightforward until two investors, shareholders, or advisers look at the same company and arrive at very different numbers. The challenge is that equity value is not simply the figure shown on a balance sheet, nor is it automatically the price suggested by the latest funding round. It depends on the company’s earnings potential, assets, liabilities, capital structure, risk, growth expectations, market evidence, and most importantly—the purpose and date of the valuation. International valuation guidance therefore recognizes several approaches rather than a single universal formula.
For UAE businesses, this matters during fundraising, acquisitions, shareholder exits, restructuring, succession planning, disputes, and investment decisions. WBS Advisory for example, identifies Discounted Cash Flow, Comparable Company Analysis, precedent transactions, and adjusted book or asset values among the methods it applies according to the company’s circumstances.
Understanding how these methods work and when each one is appropriate helps business owners focus on a valuation that can withstand commercial scrutiny rather than simply producing the highest possible number.
Why Equity Valuation Is More Than a Single Number
The first distinction to understand is the difference between enterprise value and equity value.
Enterprise value broadly represents the value of the operating business available to providers of capital, while equity value represents the amount attributable to shareholders. In many valuation exercises, an adviser first estimates enterprise value and then makes adjustments for debt, cash, non-operating assets, and other relevant claims to determine the value attributable to equity owners. IVSC guidance similarly distinguishes enterprise value from the value belonging to equity shareholders.
Consider a UAE logistics company whose operations are valued at AED 50 million. That does not necessarily mean its shareholders own AED 50 million of value. If significant borrowings must be settled as part of a transaction, the amount attributable to shareholders will be lower. Conversely, surplus cash or valuable non-operating assets may increase the amount attributable to equity.
The valuation purpose is equally important. A valuation prepared for an investor negotiation may require different considerations from one prepared for financial reporting, a shareholder exit, restructuring, or litigation. WBS Advisory specifically notes that equity valuation is used for circumstances including fundraising, acquisitions, buyouts, shareholder exits, succession planning, and disputes.
This is why a credible valuation starts by defining exactly what is being valued, why it is being valued, what date applies, and what basis of value is required before choosing a method.
Key Methods Used for Business Equity Valuation
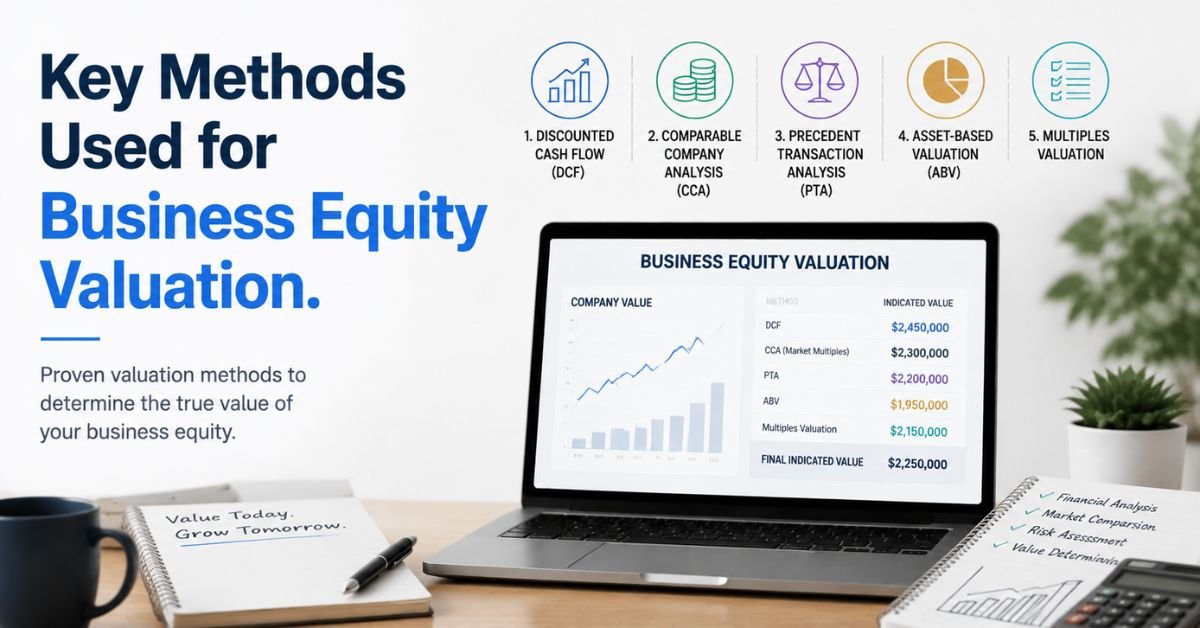
International valuation frameworks group valuation techniques broadly into the income, market, and cost approaches. IFRS 13 also makes an important practical point: a company should use techniques that fit the circumstances and for which sufficient information is available, rather than forcing every valuation into the same model.
Discounted Cash Flow Valuation
The Discounted Cash Flow, or DCF, method values a business according to the present value of the cash it is expected to generate in the future. It belongs to the income approach, which converts anticipated future amounts into a current value using an appropriate discount rate.
A DCF typically involves forecasting revenue, operating costs, taxes, capital expenditure and working-capital requirements before estimating future cash flows. Those cash flows are discounted to reflect the time value of money and the risk associated with achieving them. A terminal value normally represents the value beyond the detailed forecast period.
Suppose a Dubai-based software company is expanding quickly but currently reinvests much of its profit into sales, technology and staff. Its historical earnings alone may understate its economic potential. A carefully constructed DCF can capture the future cash generation expected from that expansion.
Its strength is also its weakness: DCF is highly dependent on assumptions. Small changes to growth, margins, terminal value or the discount rate can materially change the result. A sound valuation should therefore challenge management forecasts rather than simply accepting an ambitious business plan. IFRS guidance emphasizes that valuation techniques should reflect market-participant assumptions and current market conditions.
For privately owned UAE companies, normalization is particularly important. One-off expenses, unusual owner remuneration, related-party arrangements and temporary operating conditions may need to be examined so that projected cash flow reflects the underlying business rather than accounting noise.
Comparable Company Analysis
Comparable Company Analysis, or CCA, asks a market-based question: what are investors currently paying for businesses that resemble the company being valued?
The market approach uses prices and other information derived from transactions involving identical or comparable businesses. Valuers commonly translate this evidence into multiples and then apply an appropriate multiple to the subject company.
Depending on the industry and financial profile, relevant measures may include revenue, EBITDA, earnings or book value. The difficult part is not calculating the multiple—it is selecting businesses that are genuinely comparable.
A useful peer assessment should look beyond industry labels and consider factors such as:
- business model and customer mix;
- expected growth and profitability;
- company size and operating risk;
- geographic exposure and competitive position;
- capital intensity and financial characteristics.
IFRS 13 explicitly recognizes that selecting an appropriate multiple from a range requires judgment based on both quantitative and qualitative company-specific factors.
For example, comparing a rapidly growing UAE cloud-services provider with a mature global IT outsourcing company simply because both operate in “technology” could produce a misleading result. Economic characteristics matter more than a broad sector label.
Precedent Transaction Analysis
Precedent Transaction Analysis uses prices paid in previous acquisitions involving similar businesses. WBS Advisory identifies precedent transactions as one of the methods it uses for equity valuation, particularly alongside DCF and comparable-company analysis.
This approach can be especially useful where the purpose of the valuation is an acquisition, sale, shareholder exit, or other transaction-oriented decision because it provides evidence of what buyers have actually been willing to pay.
However, transaction prices require interpretation. A historic acquisition may have occurred under different financing conditions or market expectations. A strategic buyer may also have expected benefits that another buyer would not receive. The valuation date therefore matters: IFRS 13 requires fair-value techniques to reflect conditions at the measurement date, and it recognizes that changes in markets or newly available information can justify changes to valuation techniques or inputs.
Consequently, an old acquisition multiple should not be copied into a current UAE valuation without considering whether the transaction remains economically relevant.
Adjusted Net Asset Value
The Adjusted Net Asset Value approach starts from the company’s assets and liabilities and adjusts them toward appropriate current values rather than relying entirely on historical accounting amounts.
WBS Advisory notes that book-value analysis may be adjusted for the present market value of assets and liabilities where this method better suits the business.
This approach tends to be particularly informative for companies whose value is closely connected to identifiable assets—for example, investment holding businesses, certain property businesses, asset-intensive industrial companies, or businesses being considered from a restructuring or asset-realization perspective.
It can be less informative for a profitable service or technology business whose main economic value comes from customer relationships, intellectual property, brand, workforce capabilities and future earnings rather than physical assets recorded on the balance sheet. IFRS guidance similarly explains the cost approach in terms of the amount required to replace an asset’s service capacity, while the income approach focuses on future economic amounts.
How to Choose the Right Valuation Method
There is rarely a rule saying one method must always be used. IFRS 13 expressly allows one or multiple valuation techniques and requires the resulting indications to be evaluated according to which outcome most appropriately represents value in the circumstances. In other words, using three methods does not mean simply calculating three numbers and taking their average.
A practical rule of thumb is:
- Stable, forecastable cash flows: DCF can provide strong insight into fundamental value.
- Good publicly available peers: Comparable Company Analysis can provide useful current-market evidence.
- Sale or acquisition context: Precedent transactions may provide valuable deal-based benchmarks.
- Asset-heavy company: Adjusted Net Asset Value may deserve greater weight.
- Early-stage company: Recent financing, market benchmarks, scenario-based forecasts and the rights attached to different share classes may all need to be considered.
The final point is especially important for startups. A company may have ordinary shares, preferred shares, convertible instruments, warrants or investor liquidation preferences. The IPEV guidance warns against automatically applying the headline value from a financing round to other classes of shares when those securities have different rights and preferences.
A AED 100 million “post-money valuation,” therefore, does not necessarily mean every share can simply be valued by dividing AED 100 million by the total number of shares.
UAE-Specific Factors That Can Affect Equity Valuation
The underlying valuation principles are international, but a UAE valuation still needs to reflect the economic and regulatory environment in which the company operates.
One important consideration is related-party pricing. The UAE Federal Tax Authority states that transfer-pricing rules apply to transactions with Related Parties and Connected Persons, whether those parties are on the UAE mainland, in a Free Zone or outside the country. For transactions involving related businesses, shares or reorganizations, businesses should therefore consider whether the valuation also has tax or transfer-pricing implications and obtain appropriate tax advice where necessary.
Market evidence also requires judgment. A valuer should not assume that a company is comparable merely because it operates in the UAE, nor dismiss an international company merely because it operates elsewhere. IFRS requires market-approach comparisons to use genuinely comparable businesses and recognizes the need for adjustments based on company-specific qualitative and quantitative characteristics.
Finally, the quality of the underlying information matters. The current International Valuation Standards include dedicated requirements covering data and inputs, valuation models, and documentation and reporting, reflecting the importance of being able to explain how the valuation was reached.
For owners, that means reliable financial statements, realistic forecasts, clear debt information, shareholder agreements, details of share rights and supporting operating data are not administrative extras—they directly affect how defensible the valuation can be.
Common Mistakes That Weaken an Equity Valuation
One of the biggest mistakes is choosing the method that produces the highest result rather than the method best supported by the facts. Valuation standards emphasize appropriate techniques, sufficient information and market-relevant inputs rather than a predetermined outcome.
Another problem is treating historical transactions as permanent evidence of value. IPEV guidance makes clear that even the price from a recent investment should be reassessed at subsequent valuation dates as company performance, commercial viability and market conditions change.
Businesses should also avoid confusing enterprise value with shareholder value, overlooking debt, ignoring differences between ordinary and preferred shares, or using comparable-company multiples without understanding why one company trades at a premium to another.
Ultimately, the strongest valuation is not the one with the most complicated spreadsheet. It is the one in which the assumptions, market evidence, adjustments and final conclusion can all be clearly explained.
Conclusion
Business equity valuation works best when it is approached as a structured assessment of economic value rather than a single formula. DCF measures the value supported by future cash generation. Comparable-company analysis anchors the business against current market evidence. Precedent transactions reveal what buyers have paid for similar businesses, while adjusted net asset value focuses on the economic value of the underlying assets and liabilities. International standards recognize all of these approaches and allow methods to be combined when doing so better represents the circumstances.
For UAE companies, method selection should ultimately follow the business model, valuation purpose, available financial information, capital structure and quality of relevant market evidence. This is also consistent with WBS Advisory’s stated approach of selecting DCF, comparable-company, precedent-transaction or adjusted asset methods according to the company and its circumstances.
As businesses become more sophisticated and ownership structures more complex, the real value of professional equity valuation will increasingly lie not simply in producing a number, but in producing a number that shareholders, investors, buyers and other stakeholders can understand and defend.
Frequently Asked Questions
What is the most commonly used method for business equity valuation?
There is no single method suitable for every company. DCF, comparable-company analysis, precedent transactions and asset-based approaches are commonly used, with the choice depending on the business and available information.
Is DCF better than the comparable-company method?
Not automatically. DCF is useful when future cash flows can be reasonably forecast, while comparables are useful when reliable market evidence exists. In many valuations, both can be used as complementary evidence.
How is equity value different from enterprise value?
Enterprise value broadly reflects the value of the overall operating business, while equity value represents the value attributable to shareholders after relevant capital-structure adjustments.
Can the last funding-round valuation be used for a startup?
It can be relevant, but it should not automatically be treated as current fair value indefinitely. Changes in company performance, market conditions and the rights of different share classes must be considered.
Why might a UAE business need an independent equity valuation?
Common purposes include fundraising, acquisitions, shareholder exits, buyouts, restructuring, succession planning, disputes and investment assessment. Related-party transactions may also raise UAE transfer-pricing considerations.