A startup valuation can shape far more than the headline number in a funding announcement. It determines how much ownership a founder gives away, influences future fundraising expectations, affects investor negotiations and can become an important reference point in shareholder discussions, acquisitions and other strategic transactions. WBS Advisory similarly identifies fundraising, equity decisions, acquisitions, investor discussions and compliance-related requirements among the situations in which startup valuation becomes important.
The challenge is that startups rarely look like mature businesses. An established company may have years of revenue, profits, assets and cash-flow history. A young company may have little more than a capable team, working product, early customers and expectations about what the business could become. That is why early-stage valuation relies more heavily on market opportunity, traction, risk, future financial performance and investor expectations.
There is also no single startup valuation method that works equally well at every stage. A pre-revenue technology company should not necessarily be valued using the same approach as a rapidly growing SaaS business with several years of recurring revenue. Founders therefore need to understand not only how startup valuation methods work, but when each method produces meaningful information.
Why Startup Valuation Matters More Than the Headline Number
Founders often approach valuation by asking, “How much is my startup worth?” A more useful question is, “What valuation can the business support based on its current evidence, risks, future potential, and the purpose of the valuation?”
That distinction matters because a fundraising valuation is not automatically the same thing as an accounting or professional fair-value measurement. IFRS 13 defines fair value around the price obtainable in an orderly transaction between market participants under current market conditions. Formal valuation work may therefore require market-participant assumptions and appropriate valuation techniques rather than simply using the number negotiated in the latest funding discussion.
For fundraising, valuation also directly interacts with dilution. Suppose a founder agrees on an AED 16 million pre-money valuation and raises AED 4 million. The simplified post-money valuation is AED 20 million, meaning the new investment represents 20% of the company immediately after the round, before considering more complicated provisions or later dilution.
Convertible instruments require even more attention. Y Combinator notes that under its post-money SAFE structure, the ownership associated with a valuation-cap SAFE can be calculated from the investment amount and post-money valuation cap, making the dilution implications more visible to founders.
In practical terms, founders should evaluate valuation alongside:
- the capital actually required to reach the next important milestone;
- the percentage of ownership being sold;
- existing and future employee option pools;
- outstanding SAFEs or other convertible instruments; and
- the valuation the company may realistically support at its next financing.
A high valuation is therefore not automatically a good valuation. Dave Berkus, creator of the Berkus Method, makes a particularly useful distinction for early-stage founders: valuation is a snapshot, while the equity sold during a financing continues to affect the cap table afterward.
Startup Valuation Methods That Fit Different Stages
Professional valuation practice generally recognizes market, income, and cost approaches. IFRS 13 describes the market approach as relying on information from comparable transactions and the income approach as converting expected future amounts, such as cash flows, into a current value. Startup-specific techniques adapt these principles to businesses where historical financial information may be limited.
Early-Stage Methods for Pre-Revenue and Seed Startups
The Berkus Method is particularly useful when financial forecasts are too uncertain to carry most of the valuation. Rather than pretending that five-year revenue projections are precise, the method assigns value to milestones that reduce important startup risks: the quality of the idea, a working prototype, the management team, strategic relationships, and product rollout or early sales.
For example, imagine a UAE software startup with an experienced founding team, completed product, two strong corporate pilots, but little revenue. A Berkus-style analysis can recognize the fact that these achievements have reduced technology, execution, and market risk even though the company cannot yet demonstrate meaningful profits.
One important caution is that founders should not mechanically copy the dollar amounts shown in standard Berkus examples. Berkus himself explains that the amounts can be adjusted for geography and type of business. The underlying principle—value measurable reductions in risk—is more useful than treating the published dollar caps as universal rules.
The Scorecard Method starts differently. Instead of building value from zero, it begins with the valuation of comparable pre-revenue businesses in the relevant market and then adjusts that benchmark according to factors such as management quality, size of opportunity, technology, competition, distribution capability, and future financing needs. The Angel Capital Association’s methodology gives particularly significant weight to the strength of the team and size of the opportunity.
That makes the Scorecard Method valuable when a founder can obtain credible information about recent seed transactions. The quality of the benchmark is critical: comparing an Abu Dhabi fintech startup with a mature US SaaS company would create misleading precision rather than useful valuation insight.
Risk Factor Summation provides another perspective by explicitly examining risks surrounding the startup. The framework considers areas including management, business stage, competition, technology, fundraising, sales, legal or regulatory issues, international exposure, reputation, and exit potential. It is generally better used alongside other approaches rather than as the only source of a valuation.
This can be particularly useful when two startups have similar products but very different risk profiles. A regulated fintech business with uncertain approvals and heavy future funding requirements may deserve a different valuation adjustment from a software company with comparable commercial traction but fewer regulatory and capital constraints.
Traction-Based Methods for Revenue and Growth-Stage Startups
Once meaningful commercial data exists, founders can increasingly rely on valuation methods tied to actual market and financial performance.
Comparable Company and Comparable Transaction methods ask what investors or acquirers have paid for similar businesses. IFRS describes the underlying market approach as using prices and other information from transactions involving identical or comparable assets, liabilities, or businesses.
For startups, relevant comparisons might use revenue, annual recurring revenue, EBITDA, customers, transaction volume, or another sector-specific metric. A growing B2B SaaS startup, for example, might compare its enterprise value relative to recurring revenue against businesses with similar growth, margins, customer retention, scale, and geography.
The difficulty is finding genuinely comparable companies. A business growing at 100% per year should not automatically receive the same revenue multiple as one growing at 20%, and a private UAE startup cannot simply borrow the multiple of a much larger listed US technology company. Stage, growth, profitability, market, customer concentration, risk, and business model all matter.
Discounted Cash Flow, or DCF, estimates value from future cash flows and converts those amounts into a current value using assumptions about time and risk. That places DCF within the income approach described by IFRS 13.
DCF becomes more credible as the company develops a financial model supported by actual operating evidence. For a startup with established revenue, known unit economics, repeatable customer acquisition, and reasonable visibility into margins, DCF can provide valuable insight into what the future economics of the business imply today.
For an extremely early startup, however, small changes in assumptions about growth, margins, financing requirements, or risk can dramatically change the answer. Professor Aswath Damodaran’s work on young companies emphasizes precisely this difficulty: limited history, small current revenues, operating losses, uncertainty about future growth, and survival risk make young businesses especially challenging to value.
The Venture Capital Method approaches the problem from the investor’s expected exit. The investor estimates what the company could be worth at a future liquidity event and works backward to determine what the business is worth today given the required investment return and risks. Harvard Business School describes the method as forecasting a future value and discounting that terminal value back to the present.
For founders, its greatest value is not necessarily producing the final valuation. It helps explain investor thinking. A venture investor considering an AED 5 million investment will ask whether a realistic future exit can generate enough value to compensate for startup risk, future dilution, and the investor’s required return.
How Founders Should Choose the Right Valuation Method
One of the biggest valuation mistakes is expecting one formula to produce the “correct” answer.
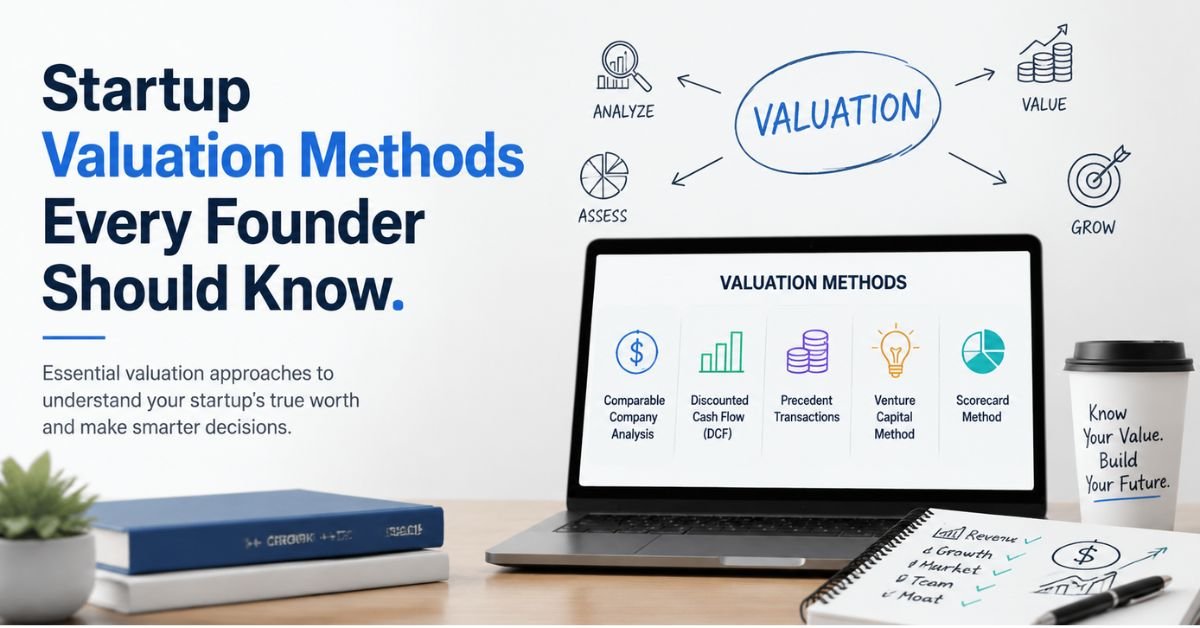
A better approach is triangulation: use two or more suitable methods, understand why they produce different results, and identify a defensible valuation range. Gust’s guidance on early-stage valuation similarly recommends using multiple methods rather than relying solely on Risk Factor Summation. WBS Advisory also describes using different methods—including Berkus, Scorecard, Risk Factor Summation, DCF, and comparable transactions—depending on the startup’s circumstances.
Consider three simplified situations.
A company with a prototype but no revenue may emphasize Berkus and Scorecard analysis. A business generating recurring revenue but still burning significant cash may give more weight to comparable-company analysis and a scenario-based DCF. A Series A company with established economics and a plausible exit path may use market multiples, DCF, and the Venture Capital Method together.
Founders should also avoid several common errors: selecting only comparables that support a desired number, presenting aggressive forecasts without operational drivers, confusing a SAFE valuation cap with a definitive company valuation, ignoring future dilution, and treating the previous funding-round valuation as permanently valid. Market conditions and company-specific evidence can change, so valuation inputs must remain current. IFRS valuation principles likewise emphasize current market conditions and the appropriate use of available observable information.
The objective should not be to manufacture the highest possible number. It should be to create a valuation argument that survives investor questions.
What UAE Founders Should Consider When Valuing a Startup
UAE founders operate in an increasingly active technology and investment ecosystem. Hub71 reported in June 2026 that companies within its Abu Dhabi ecosystem had surpassed $2.7 billion in funding, while ADGM positions its startup ecosystem around access to venture capital firms, investors, corporates and regional growth opportunities.
That does not mean UAE startups should automatically command a valuation premium. It means founders need locally relevant evidence.
A good UAE startup valuation should examine:
- recent transactions involving businesses at a similar stage, preferably in the UAE, GCC, or another genuinely relevant market
- whether the business has demonstrated UAE traction only or has credible GCC and international scalability;
- licensing and regulatory requirements that could either reduce uncertainty or increase execution risk;
- customer concentration, recurring revenue quality, margins, unit economics, and future capital requirements; and
- the value and defensibility of technology, intellectual property, partnerships, contracts, and the founding team.
Geography is particularly important when applying the Scorecard or comparable-transactions methods because these approaches depend on appropriate market benchmarks. The Angel Capital Association explicitly notes geography as an important consideration when establishing the starting benchmark for its Scorecard approach.
Founders should also distinguish between a valuation prepared for negotiating a financing round and one required for a formal transaction, shareholder matter, acquisition, financial reporting, or other professional purpose. WBS Advisory’s UAE startup valuation service for example, describes customized analysis based on financial forecasts, market conditions, startup-specific methods, business models, growth plans, risks and investor readiness.
Conclusion
Startup valuation is ultimately an exercise in converting uncertainty into a defensible range of value.
Pre-revenue founders should focus heavily on evidence that reduces execution, product, market, financing, and team risk. As traction develops, market comparisons become more meaningful. As revenue and cash-flow visibility improve, DCF and other income-based techniques become increasingly useful. The Venture Capital Method adds another important perspective by showing how investors connect today’s price with potential future returns.
The strongest valuation therefore rarely comes from forcing every startup into one formula. It comes from selecting methods appropriate to the company’s stage, using credible UAE and sector benchmarks, building realistic financial assumptions, accounting for risk, and reconciling the different indications of value.
For founders, that approach has a practical advantage beyond securing a funding round: it creates a clearer understanding of what is genuinely creating value in the business and which milestones need to be achieved before the next valuation discussion.
Frequently Asked Questions
What is the best startup valuation method for a pre-revenue company?
Berkus, Scorecard, and Risk Factor Summation are commonly suited to pre-revenue businesses because they can evaluate team quality, market opportunity, product development, traction, and risk without depending heavily on historical profits.
What is the difference between pre-money and post-money valuation?
Pre-money valuation is the company’s value immediately before new investment. In a straightforward priced round, post-money valuation equals the pre-money valuation plus the new investment.
Can DCF be used to value a startup?
Yes. DCF can be useful when forecasts are supported by credible operating data. It becomes less reliable when an early-stage company’s future revenue, margins, financing requirements, and survival are extremely uncertain.
Is a SAFE valuation cap the same as a startup valuation?
Not necessarily. A valuation cap is a contractual term that influences the price at which a SAFE converts into equity. It should not automatically be treated as a formal valuation of the entire business for every purpose.
How often should a UAE startup update its valuation?
A valuation should be reconsidered when material information changes for example, after significant fundraising, major new revenue or contracts, product milestones, acquisitions, substantial changes in forecasts or shifts in relevant market conditions. Professional valuations should reflect the purpose and measurement date rather than relying indefinitely on an old funding-round number.